Independent owner-maintained website. The Cantrice Court name is used solely to identify the Cantrice Court community in Simi Valley, California, and the subject of this site. This website is not affiliated with, sponsored by, authorized by, or operated by the Cantrice Court Condominium Owners' Association, its Board of Directors, or its management company.
The short answer: the current documents show about $32.7 million of stated property capacity. The important answer: the signed Helix application now reveals the building values used to support that tower - including a uniform $164 per living square foot valuation - and Helix can limit recovery for an individual building or structure to 110% of the value on file.
Last updated September 22, 2026 · Source record reviewed for this release
START HERE
Three numbers. One unresolved question.
STATE FARM$22,901,900Underlying property coverage
+
HELIX$9,806,516Excess of $22,901,900
=
STATED CAPACITY$32,708,416Per occurrence, subject to policy terms
Do not read “$32.7 million” as a guaranteed check. The total limit and the value assigned to each building are different things. Helix's 110% Margin Clause can matter in a multi-building catastrophe if the values submitted to Helix are too low.
NEW: THE SOV HAS BEEN LOCATED
The excess policy was built on a $164-per-square-foot valuation.
The signed August 28 Helix application includes the Association's Statement of Values. It lists $26,985,216 of building replacement cost plus $5,723,200 of garage replacement cost, for a total insured value of $32,708,416. Residential building values use a uniform $164 per living square foot.
Why this matters: Helix says its liability for any one building or structure cannot exceed 110% of that property's stated value. If those values materially understate actual reconstruction cost, unused policy limit elsewhere does not automatically erase the building-specific cap.
Two verification records still needed:1. Helix Schedule of Covered Locations2. Helix Schedule of Underlying InsuranceSee source documents and status →
One number still needs reconciliation: State Farm separately lists $22,613,700 for buildings and $288,200 for business personal property. Helix attaches at $22,901,900 - the sum of those two State Farm limits. For a building-only catastrophe, owners should be able to see exactly how Helix's Schedule of Underlying Insurance treats that split before assuming there is no attachment gap.
WHAT CHANGED?
The old 60% problem was real. The new excess layer improves the headline number.
In the Association's owner-vote presentation, the Board described the then-current State Farm policy as “60% replacement coverage” and said a 100% replacement-cost policy was substantially more expensive. The current State Farm declarations now show $22,613,700 of blanket building coverage plus $288,200 of business personal property, totaling $22,901,900. The later Helix policy adds $9,806,516 above that layer.
Board source: Association “Summary of Owner Ballots” presentation, which states: “Current State Farm policy (60% replacement coverage).” Source copy is on file with this site.
BOARD'S EARLIER 60% DESCRIPTION
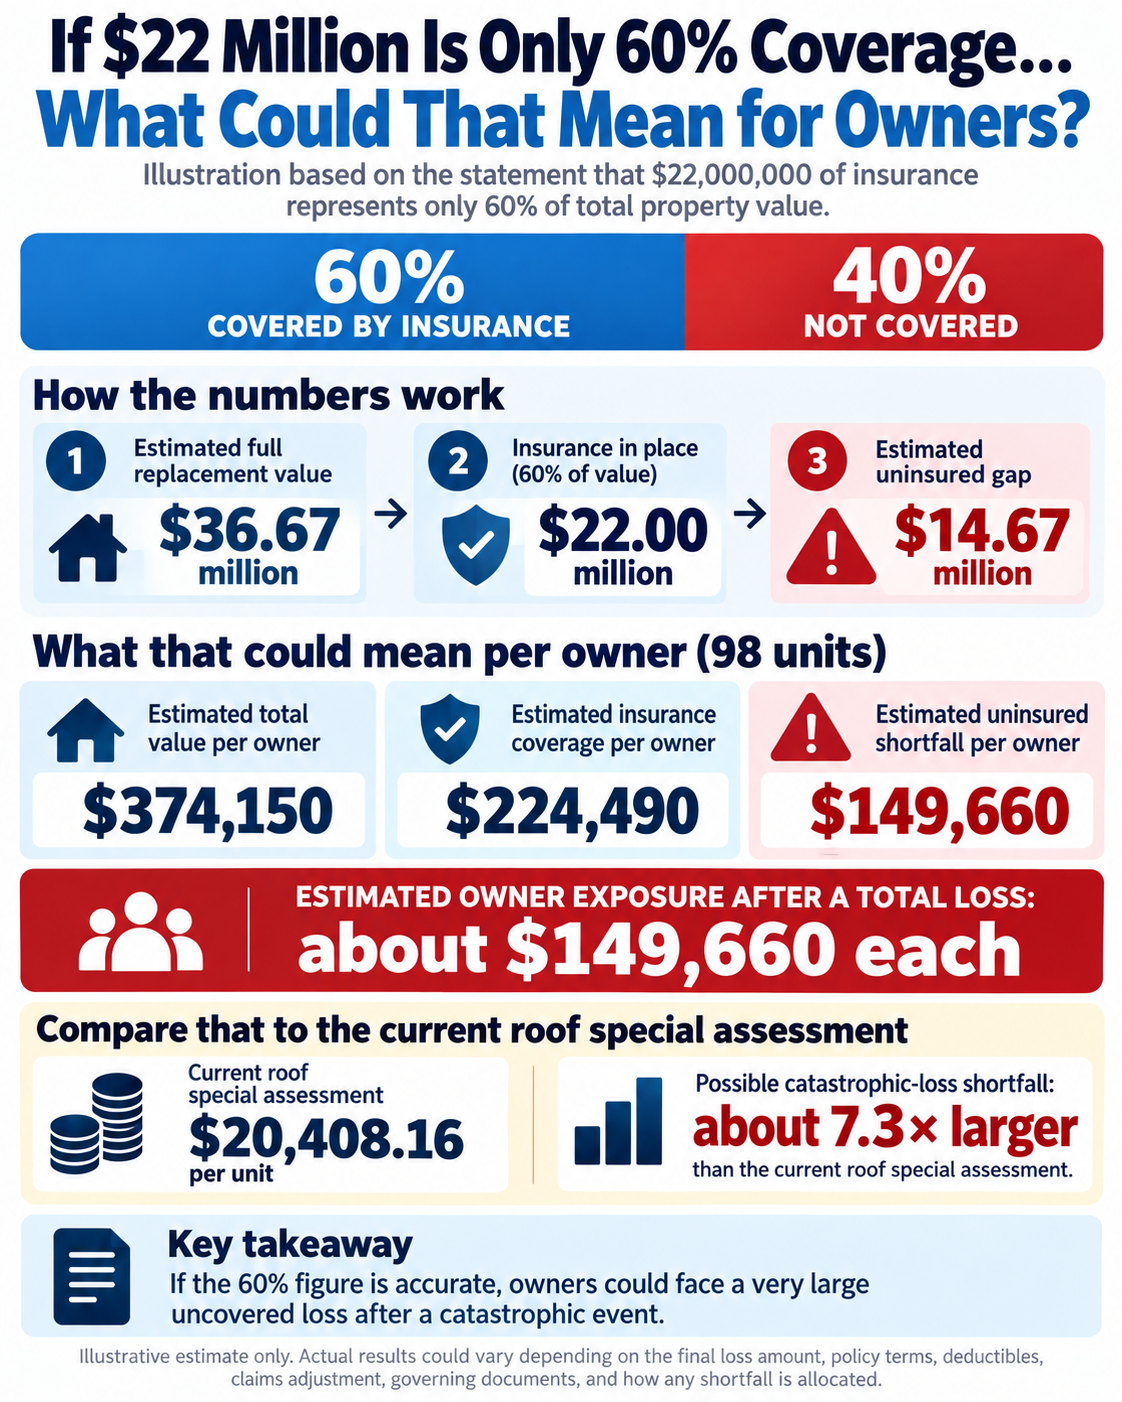
About $22 million = 60%
If $22 million represented only 60% of replacement value, the implied full value was about $36.67 million. On that historical assumption, the uninsured difference was about $14.67 million - roughly $149,660 per owner across 98 units if allocated equally.
CURRENT DOCUMENTED LAYERS
$32.708 million stated capacity
Using that same $36.67 million implied replacement-value benchmark only as an illustration, the new nominal gap would fall to about $3.96 million, or about $40,390 per owner if allocated equally. That is still almost 2x the current $20,408.16 roof assessment - before deductibles or building-specific limitations.
Historical illustration only. This visual shows the exposure implied by the Board's earlier 60% description before the new Helix excess layer. It is not a statement of the current verified uninsured amount.
THE NEW VALUATION QUESTION
The SOV solves one mystery - and creates a more important one.
SOV building replacement cost$26,985,216
SOV garage replacement cost$5,723,200
SOV total insured value$32,708,416
Residential building rate used$164 / sq. ft.
The Statement of Values is not missing anymore. It is in the signed Helix application and was signed by Board President Mark Reynders on August 28, 2026. The key question is now whether those submitted replacement-cost values were adequate when the excess policy was bound.
A number that needs reconciliation: the Board previously described the State Farm policy as “60% replacement coverage.” If that statement were literal and applied to the current $22,613,700 building limit, it would imply about $37.69 million of full building replacement value. The Helix SOV lists only $26.99 million of building replacement cost - a difference of about $10.70 million. These may reflect different assumptions, dates, valuation methods, or scopes, so the difference is a question requiring explanation - not proof by itself that the SOV is wrong.
WHY THE MARGIN CLAUSE MATTERS
If a major wildfire destroys multiple buildings, will the building values support the claim?
1
Helix sits above State Farm
Helix does not replace the underlying policy. Its $9,806,516 layer attaches above $22,901,900 and responds subject to the policy's terms.
2
Each building has a hard valuation reference
The Helix Margin Clause says liability for one building or structure cannot exceed 110% of the value assigned to it in the latest Statement of Values or other valuation information on file. The signed SOV now shows those values.
3
Only listed locations count
Helix defines a Covered Location by reference to the most recent Schedule of Covered Locations accepted by Helix.
Bottom line: the headline limit is real, and the SOV is now known. The unresolved question is whether the $164-per-square-foot building values are sufficient for catastrophic reconstruction, and whether Helix's accepted Covered Locations and underlying-insurance schedules match the Association's understanding of the coverage.
COVERAGE CALENDAR
The two property layers do not expire on the same date.
STATE FARM UNDERLYINGJan. 30, 2026 - Jan. 30, 2027
HELIX EXCESSAug. 31, 2026 - Aug. 31, 2027
Helix requires the underlying insurance identified in its schedule to remain in force at not less than the required underlying limits. That means the State Farm renewal after January 30, 2027 matters because Helix continues for another seven months. The renewal should be checked against Helix's underlying-insurance requirements when it is issued.
Also worth knowing: Helix is a nonadmitted / surplus-lines insurer. Its policy notice states that it is not protected by California insurance guarantee funds if the insurer becomes insolvent. That does not mean the policy is invalid; it is a disclosure about the type of insurer and regulatory protections.
DOCUMENT STATUS
What we have - and what we still need.
Record
Status
Why it matters
2026-27 State Farm policy/declarations
RECEIVED
Confirms the $22,901,900 underlying property amount and listed premises.
2026-27 Helix excess policy
RECEIVED
Confirms $9,806,516 excess of $22,901,900 and the controlling excess-policy terms.
Statement of Values / building-value schedule submitted to Helix
RECEIVED / LOCATED
Signed SOV lists $26,985,216 building RC + $5,723,200 garage RC = $32,708,416 TIV, using $164 per living square foot for residential buildings.
Schedule of Covered Locations accepted by Helix
STILL NEEDED
Needed to verify exactly which locations Helix recognizes as covered.
Helix Schedule of Underlying Insurance
STILL NEEDED
Needed to verify the underlying policies and limits Helix actually relies upon.
Status correction: the September 17 owner follow-up requested the current State Farm declarations. Those declarations have since been received, so that part of the request is now satisfied. The Statement of Values has also now been located inside the signed Helix application. The Covered Locations and Underlying Insurance schedules remain the material missing verification items in the record available to this site.
WHAT WOULD A $30 MILLION FIRE LOOK LIKE?
The total limits appear large enough on paper - but a catastrophic multi-building claim is not just one big bucket.
Illustrative covered property loss$30,000,000
State Farm underlying layerup to $22,901,900
Remaining loss reaching excess layer$7,098,100
Helix stated excess limit$9,806,516
If the loss is covered by both layers, the affected locations and building values support the claim, and no exclusion, sublimit, deductible or other limitation changes the result, the stated limits appear sufficient for that simplified $30 million example. But the Helix Margin Clause means the building-by-building values can matter even when the total policy tower looks large enough.
WHAT DID THE EXCESS COVERAGE COST?
About $39,000 before financing - more than $41,000 on the signed payment schedule.
Helix premium$35,000
Policy tax + stamping + broker fee$2,376.96
Proposal / finance amount$38,951.96Includes $1,575 risk-management fee shown in proposal
The signed finance agreement shows an $11,837.99 down payment and ten monthly payments of $2,917.41. These are costs of obtaining the excess layer; they do not themselves establish what a future claim will pay.
SOURCE DOCUMENTS
Read the policies yourself.
SIGNED HELIX APPLICATION
Statement of Values - August 28, 2026
The one-page SOV signed with the Helix application. It lists each building, square footage, building replacement cost, garage replacement cost, the $164-per-square-foot residential building rate, and the $32,708,416 total insured value.
The owner request explaining why the current declarations, Statement of Values and Covered Locations schedule matter. The current State Farm declarations have since been received.
The full signed Helix application contains e-signature audit metadata, including IP-address information that is not necessary for owners to understand the coverage. The site therefore posts the substantive one-page Statement of Values separately, together with the issued policy and other material coverage records.